In September, strong economic growth and stubborn inflation pulled different parts of markets in separate directions. Shares held up well overall for sterling investors, while bond markets came under further pressure. Renewed conflict involving Iran pushed oil prices higher, and central banks in the US, Europe and Japan raised interest rates. The Bank of England, however, chose not to raise and opted for a pause.
Equities: technology leads and currency helps
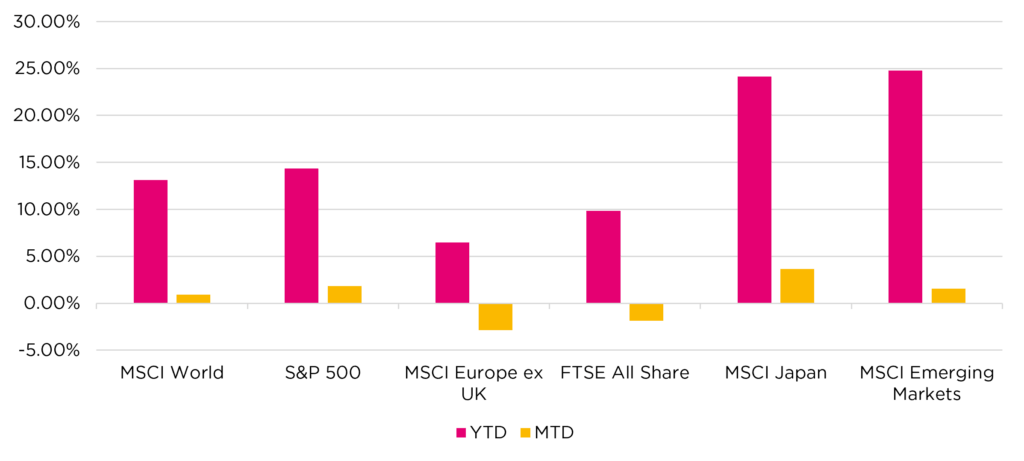
Equity returns were mixed but, for UK-based investors, a weaker sterling helped overseas equity returns. Sterling fell around 2% against the US dollar and, when the pound weakens, overseas investments are worth more once converted back into sterling. The S&P 500 fell 0.4% in dollar terms but rose by roughly 1.8% in sterling. This strong performance was mainly due to a narrow set of stocks, with the technology-heavy Nasdaq rising 4.2% in sterling, supported by continued enthusiasm for AI, while more traditional companies that are sensitive to interest rates lagged. Meta was a particularly strong performer over the month, due to the launch of its consumer AI agent Muse and it hitting number 1 on the Apple App Store charts.
Emerging markets were again among the stronger regions. Taiwan’s stock market reached a record high, and South Korean memory-chip exports rose by more than 350% compared with a year earlier, supporting Samsung Electronics and SK Hynix.
Closer to home, the FTSE All Share fell 1.9%, as stronger than expected economic growth and increased domestic inflation impacted consumer-facing and rate-sensitive stocks. Nevertheless, the index’s year to date performance remains close to double digits. European shares fell around 2.5% as rising bond yields reduced investor appetite, while in Japan the Nikkei edged higher despite the Bank of Japan’s rate rise due to both exposure to AI-related stocks and investor enthusiasm around corporate governance reforms.
Past performance is not necessarily a guide to future performance and is not guaranteed. Performance comparisons are included for illustration purposes only, there are no specific benchmarks.
Figure 1: Equity Market Returns (Source: Bloomberg, September 2026)
Central banks respond to higher energy prices
Middle East tensions flared again in early September, with fresh US and Iranian strikes and attacks on shipping in the Strait of Hormuz, through which around a fifth of the world’s oil normally passes. Hopes of a peace deal lifted sentiment late in the month, before the US rejected Iran’s latest proposal.
Central banks responded to higher energy costs feeding through to prices. The US Federal Reserve raised interest rates for the first time since 2023, by 0.25% to 4.00%, and signalled one further rise this year.
The European Central Bank and the Bank of Japan also raised rates, the latter to its highest level since 1995. In the UK, the Bank of England held interest rates at 3.75%, although three of its nine policymakers voted for an increase. Inflation in the UK rose to 3.1% in August, driven largely by fuel prices, and the Bank expects it to peak slightly above 4% in early 2027. Growth has been resilient, with GDP rising 0.4% in July, led by technology services.
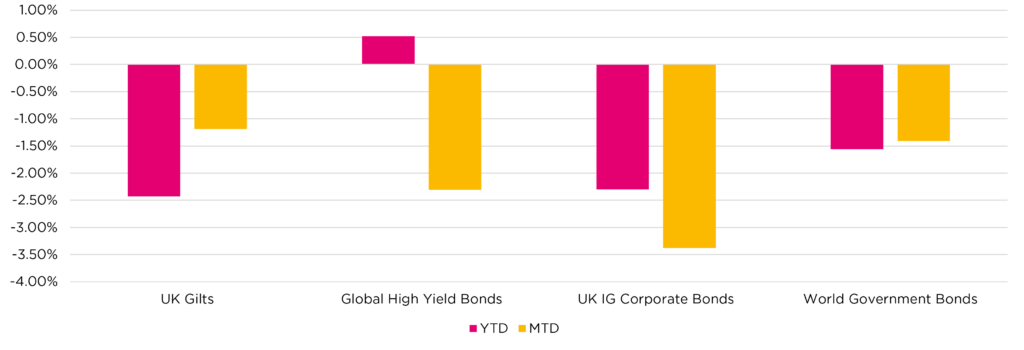
Global government bonds delivered negative returns as yields rose again. Bond prices fall when yields rise, reflecting investors’ demands for higher returns given a stronger growth outlook, central banks willingness to hike interest rates and continued heavy government borrowing.
In the US, longer-dated Treasury yields continued their increase to levels not since 2007, with the 30yr yield hovering around 5.6%. In the UK, the 30-year gilt yield was close to reaching 6% on 30 September, its highest level since 1998, while the 10-year yield touched levels last seen in 2008. This matters ahead of the Budget on 28 October, as higher borrowing costs reduce the Chancellor’s room for manoeuvre (also known as “the fiscal headroom”). For investors, however, gilts now offer some of the highest levels of income in decades.
Past performance is not necessarily a guide to future performance and is not guaranteed. Performance comparisons are included for illustration purposes only, there are no specific benchmarks.
Figure 2: Fixed income returns (Source: Bloomberg, September 2026)
Oil rises as gold loses its shine
Brent crude rose around 14% over the month, ending close to $100 a barrel, on continued disruption in the Strait of Hormuz. Gold, which rallied strongly in August, gave back much of that gain, falling around 7% in dollar terms. Higher interest rates and a stronger dollar make gold, which pays no income, less attractive than cash and bonds.
Summary
September highlighted both the strength of the global economy and the challenge it creates. Shares, supported by AI-related earnings, have so far absorbed higher interest rates, while bonds have borne more of the pressure. For long-term investors, spreading money across regions, asset types and currencies helps smooth the journey.